Insurance appraisal for property owners
Fire damage insurance appraisal in South Carolina
Fire damage insurance appraisal in South Carolina may address a loss amount that remains disputed after the first estimates and payments. The disagreement could concern rebuilding part of the home, cleaning affected materials, or valuing damaged belongings. Those questions need separate records even when they come from the same fire.
Our background includes extensive fire claim work and several years of insurance appraisal experience. Our approach is to define the disputed work and support the valuation with details that can be checked.
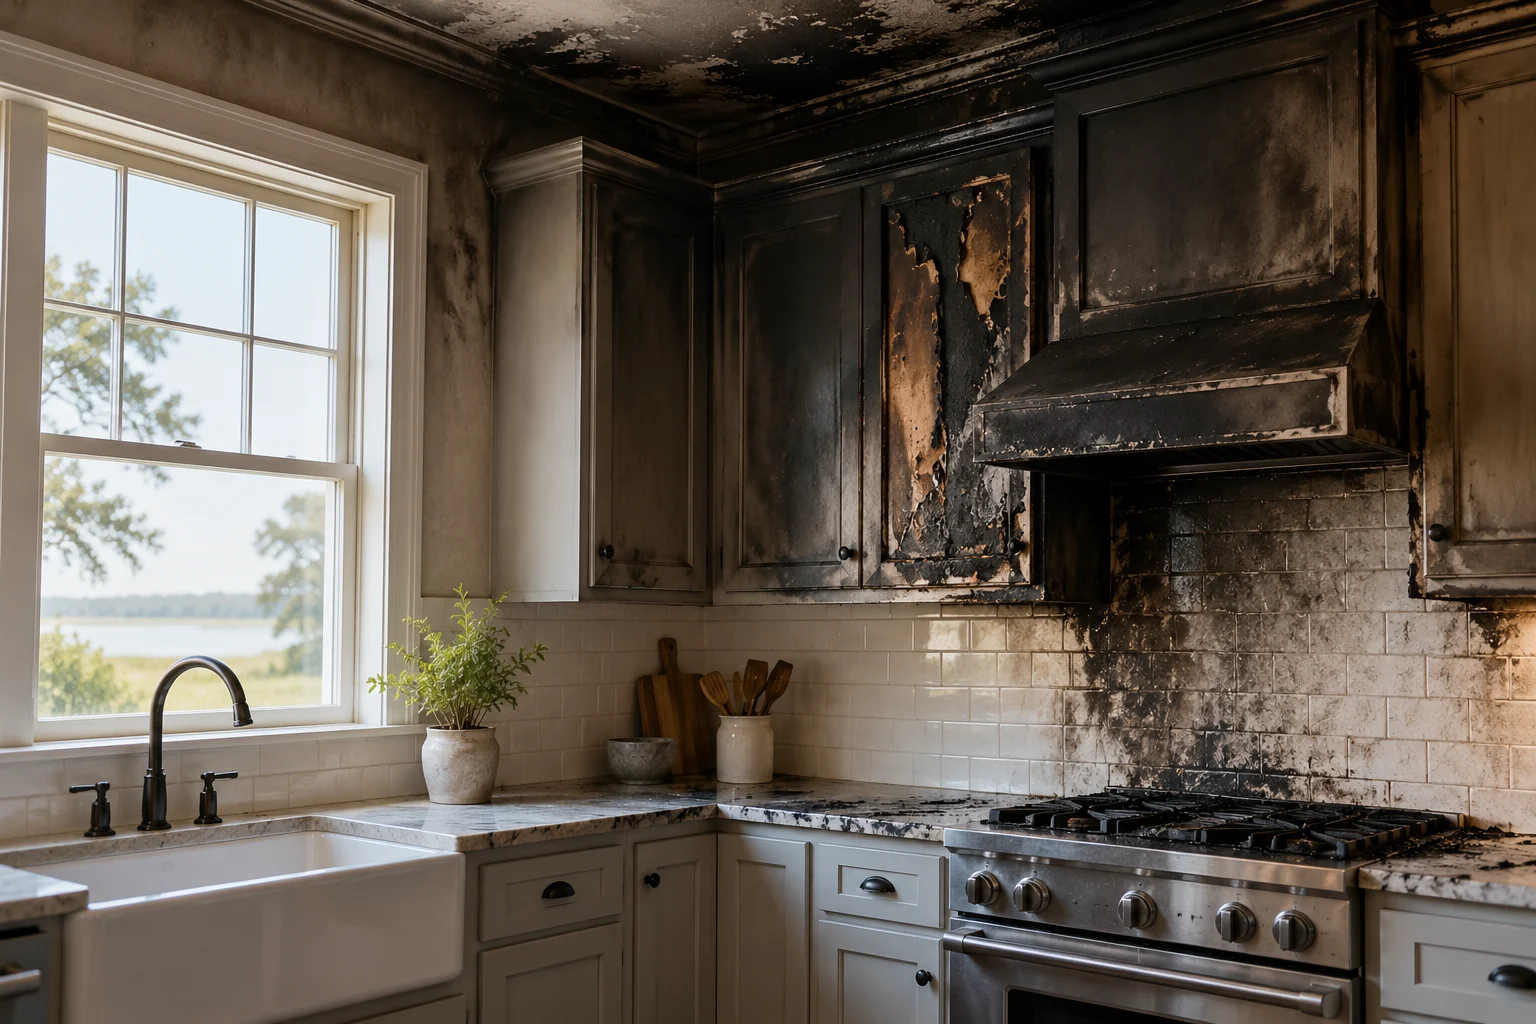
Fire damage insurance appraisal
First, identify which part of the loss is being considered for appraisal. A building estimate and a contents inventory do different jobs. If the building amount is settled but belongings remain disputed, the appraisal discussion should clearly identify that remaining issue.
Review the policy and the insurer's current position before choosing the process. A disagreement about value is not the same as a legal coverage dispute. Get appropriate advice about the policy's requirements and the effect of an award before moving forward.
Value the repair tasks by affected area
Rooms can be affected in different ways after a fire. One may have direct burning, while another has damage from smoke or water. Inspection findings and professional repair explanations help show why different materials need different treatment.
We use photos, measurements, and Xactimate estimates to connect that evidence to the repair scope. More than two decades of estimate writing help us explain the quantities and work involved. The estimate should describe supported repairs rather than apply the same assumption to every room.
Give damaged belongings a complete record
Our experience includes a fire claim where the homeowner's first contents list missed much of what had been lost. That experience highlights a practical problem: it is hard to remember a household from a blank page. Old photos, order histories, and room-by-room notes can help rebuild the record.
Completeness and accuracy need to work together. Describe the actual items, their age, condition, and available ownership evidence. If a value is disputed, identify the item's model or qualities before comparing replacement examples. A policy limit alone does not establish what the belongings were worth.
Keep the valuation discussion focused
Preserve cleanup reports and photos taken before materials were removed. If repairs have started, keep each estimate version and the invoices for completed work. This helps explain the original condition and prevents the same task from appearing twice.
Our South Carolina work includes Charleston, Columbia, Myrtle Beach, and Hilton Head. Bring the policy, competing estimates or inventories, inspection records, and appraisal correspondence. Discuss the assignment and fees before an appointment, including any prior involvement with the claim. Our focus is an honest valuation and clear updates while the work proceeds, without treating another fire claim's outcome as a promise for yours.
A clearer next step
Let's talk about your property claim.
Tell us what happened, where things stand with your insurer, and what's still unresolved. We can discuss the work your situation needs and whether our services are a fit.