Insurance appraisal for property owners
Residential insurance claim appraisal in South Carolina
Residential insurance claim appraisal in South Carolina may help address a disagreement about the amount of damage to your home. The insurer may have accepted that a loss happened, yet its estimate still describes a much smaller repair job than the one your contractor proposes.
We review the repair details behind that gap. Our experience includes several years of insurance appraisal and more than two decades of estimate writing, supported by field and desk adjusting work.
Residential insurance claim appraisal
Start by identifying the areas still in dispute. A kitchen floor, a damaged ceiling, and a bathroom wall may each involve different materials and measurements. Describing the disagreement room by room can make it easier to see what an appraisal assignment would need to address.
Keep the insurer's position in writing. If the disagreement concerns whether the loss is covered at all, do not assume a home damage appraisal will resolve it. The policy and the nature of the dispute should guide the next step.
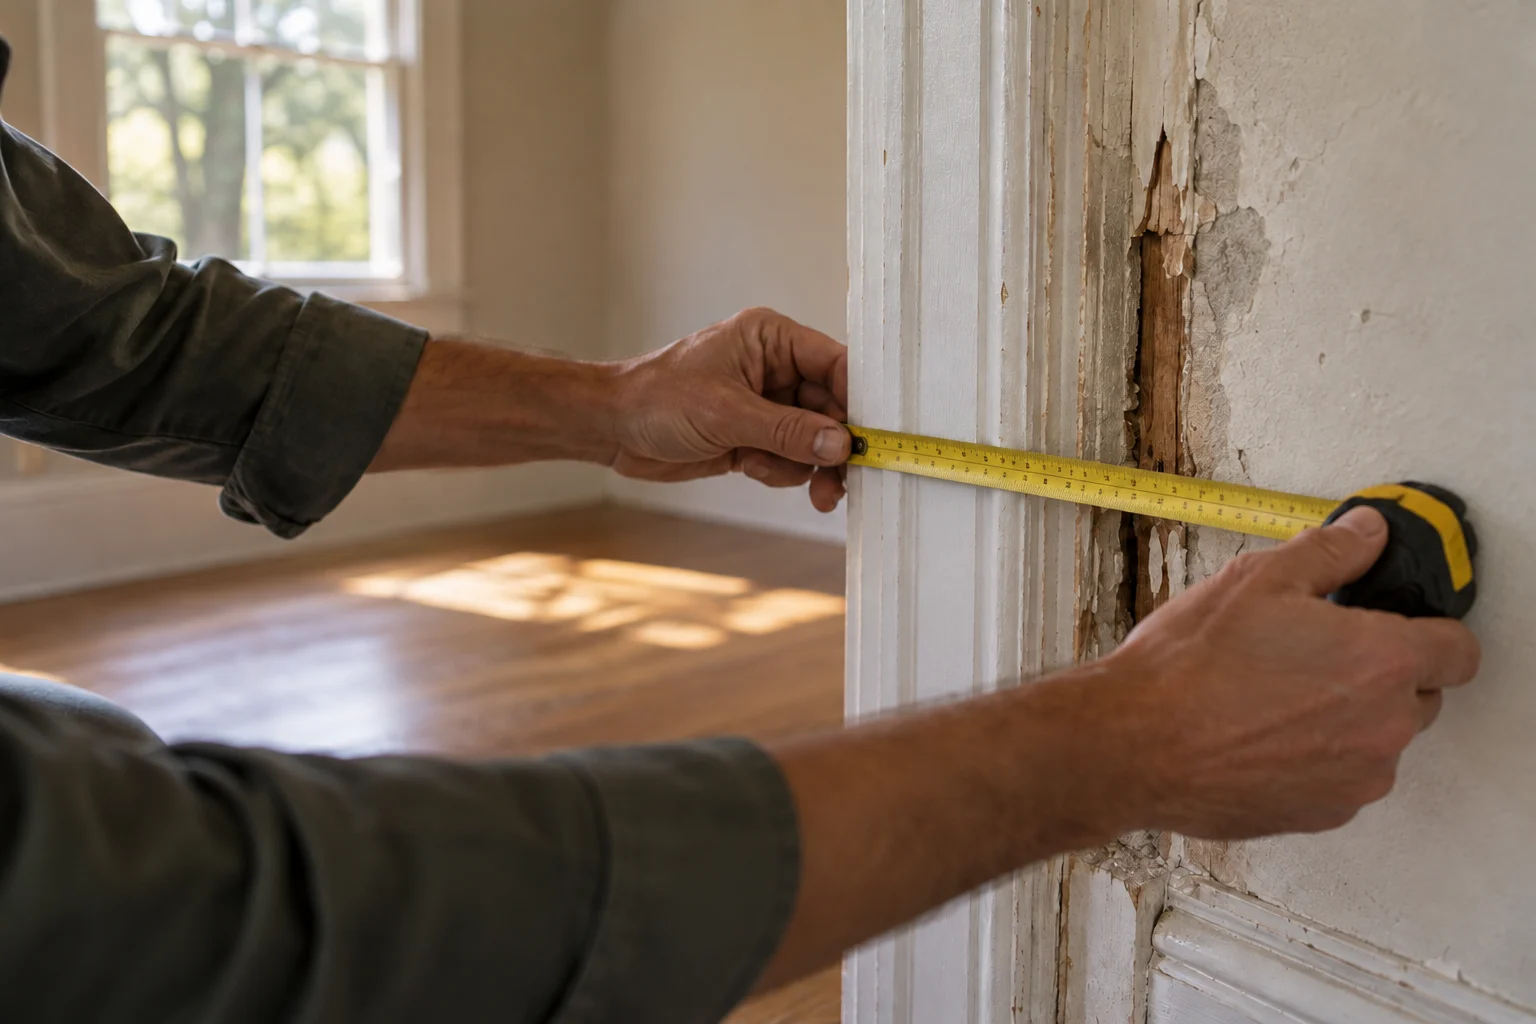
Compare the home repair work in detail
A contractor's total and an insurer's total may include different tasks. One may list new material alone, while another includes removal and preparation. Check whether the estimates describe the same surfaces, quantities, and finishes before treating the difference as a pricing problem.
We use Xactimate with photos and measurements to support the estimate. Our work draws on more than two decades of experience writing estimates in the program. The value of that experience is an ability to explain the repair work, not simply to produce a longer list of charges.
Preserve the evidence as repairs progress
Some homeowners need to begin work before a dispute is resolved. Keep dated photos, inspection reports, and invoices so the original condition can still be understood. Ask contractors to record newly exposed damage before they cover it again.
Also separate building repairs from damaged belongings. A room repair estimate does not establish the value of everything that was inside it. If personal property is part of the proposed appraisal, identify that portion clearly and keep its supporting records organized.
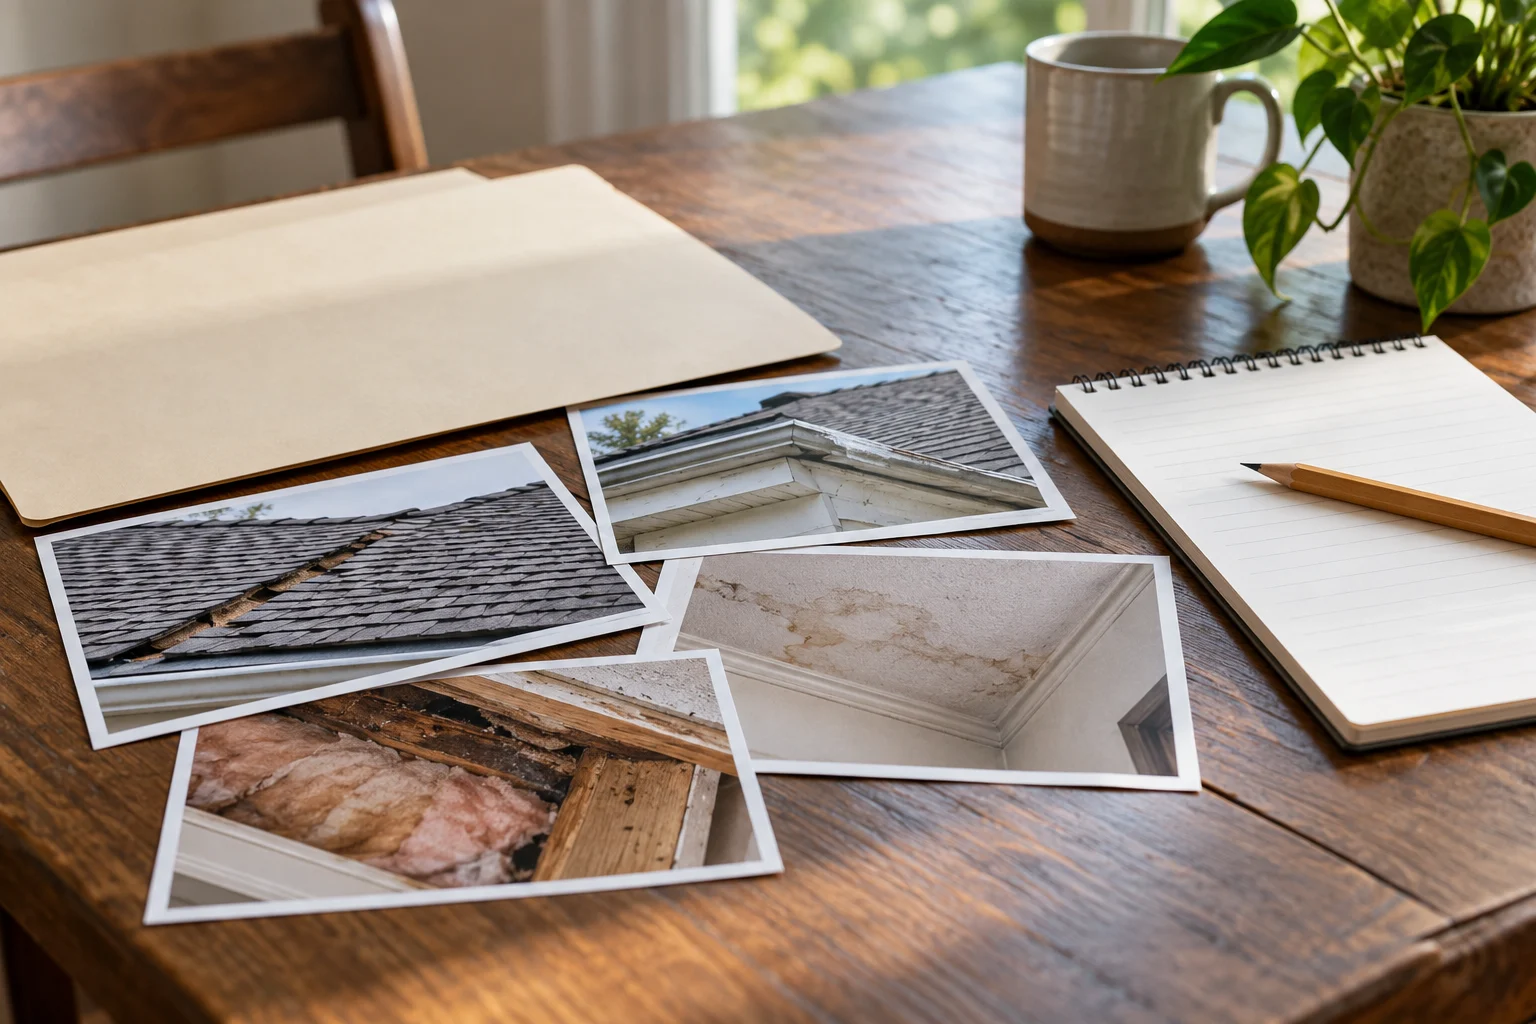
Make an informed appointment
Our approach includes honest estimates and direct updates. We also recognize that appraisal can take time. Discuss the scope, fees, and policy requirements before an appointment, along with any prior involvement we may have had in the claim. The proposed role must fit the assignment.
Our South Carolina work has focused on Charleston, Columbia, Myrtle Beach, Hilton Head, and the eastern part of the state. Bring the full policy, estimates, photos, payment letters, and any appraisal correspondence. Explain which repairs remain unfinished and which items are still disputed. That gives us a clear basis for discussing whether our appraisal work is appropriate for your home and what information the review will require.
A clearer next step
Let's talk about your property claim.
Tell us what happened, where things stand with your insurer, and what's still unresolved. We can discuss the work your situation needs and whether our services are a fit.