Insurance appraisal for property owners
Roof damage insurance appraisal in South Carolina
Roof damage insurance appraisal in South Carolina may be worth discussing when the remaining disagreement is what the roof loss is worth. You may have already provided the contractor's estimate and still be receiving the same answer from the insurer. The next useful step is to identify the repair details behind the gap.
Our wind and hail experience and long history of estimate writing help us examine those details. We approach the valuation through documented damage, measurements, and the work described in each estimate.
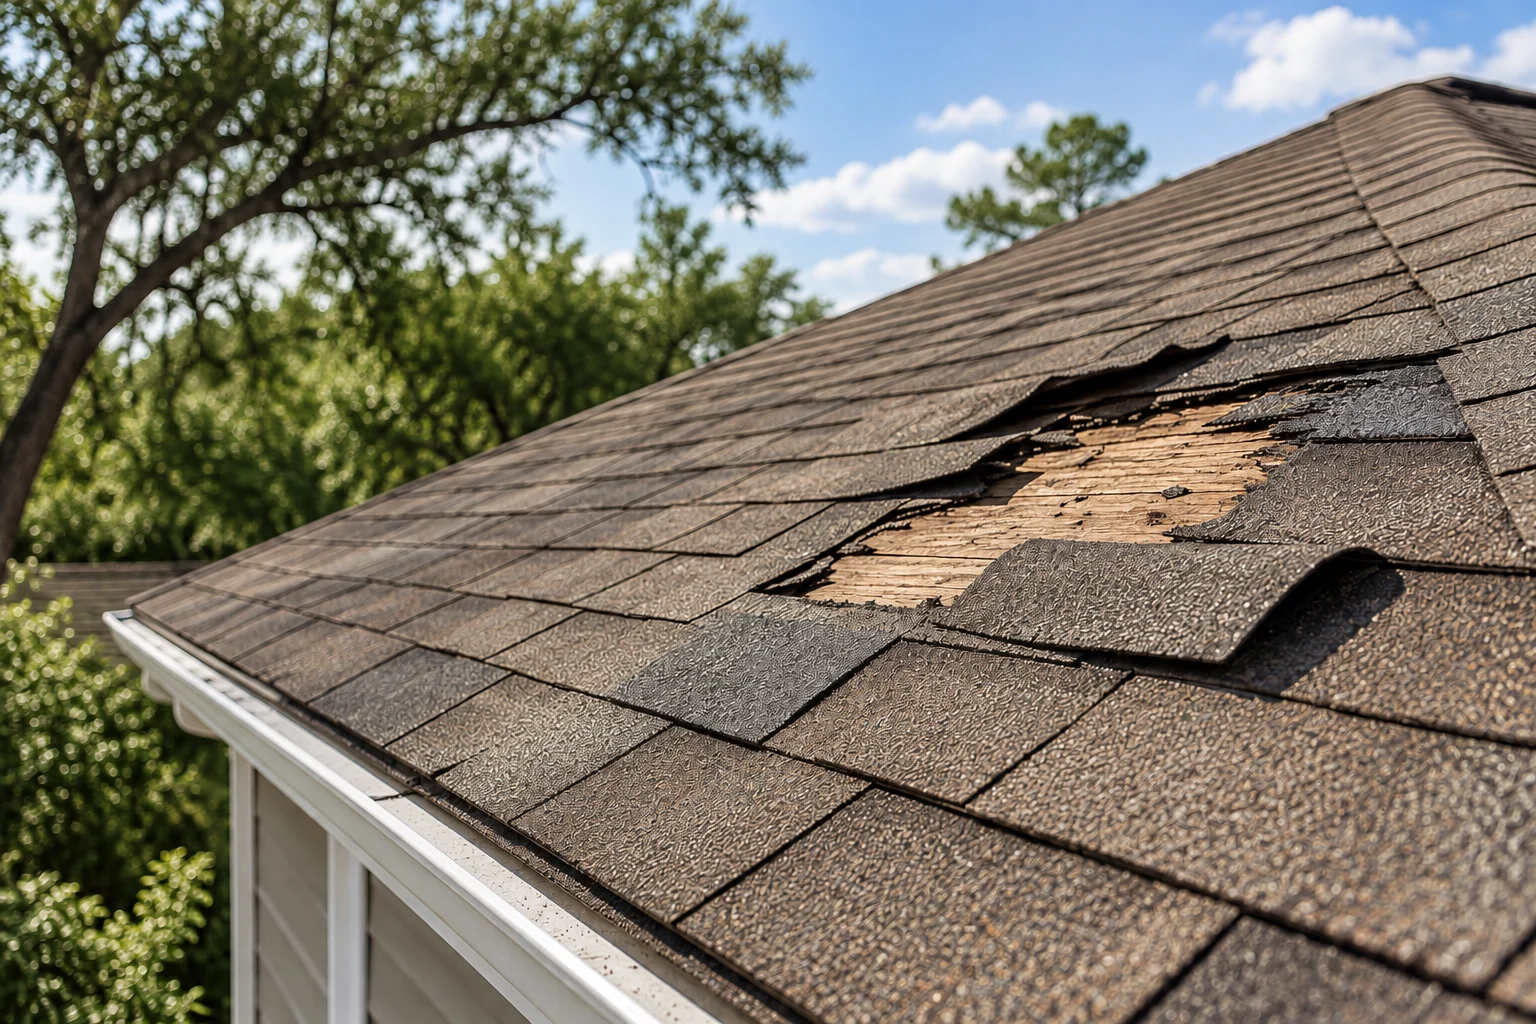
Roof damage insurance appraisal
Begin with the insurer's written position and the actual appraisal clause. An accepted loss with disputed repair costs is different from a complete denial. Questions about whether a particular dispute belongs in appraisal need to be addressed before the valuation work starts.
Identify the affected roof areas and what each estimate proposes. One may price a limited repair while another prices a larger scope. The difference should be described openly rather than hidden inside two totals that appear to be pricing the same job. If the disputed storm damage extends beyond the roof, storm damage insurance appraisal may be relevant to the wider repair scope.
Make the roof measurements useful
Keep roof diagrams, inspection photos, material descriptions, and contractor findings together. Label the areas shown in the photos so someone reading the file can connect them with the estimate. Explain any revised measurements and preserve the earlier versions.
Our work draws on more than two decades of Xactimate experience. Our field and desk adjusting background helps us connect the physical inspection with the estimate on paper. A quantity should be supported by the measurements, and a repair item should have a clear reason for being included.
Explain the proposed work, not just the total
Review the tasks needed to carry out the proposed repair. Removing damaged materials, reaching the work area, and restoring affected components may involve different costs. The question is which tasks belong to the documented job and how they have been priced.
A contractor's repair explanation can be useful when the method is disputed. An appraisal review should evaluate that information on its merits. It should not begin with an automatic assumption that either the contractor's amount or the insurer's amount must be correct.
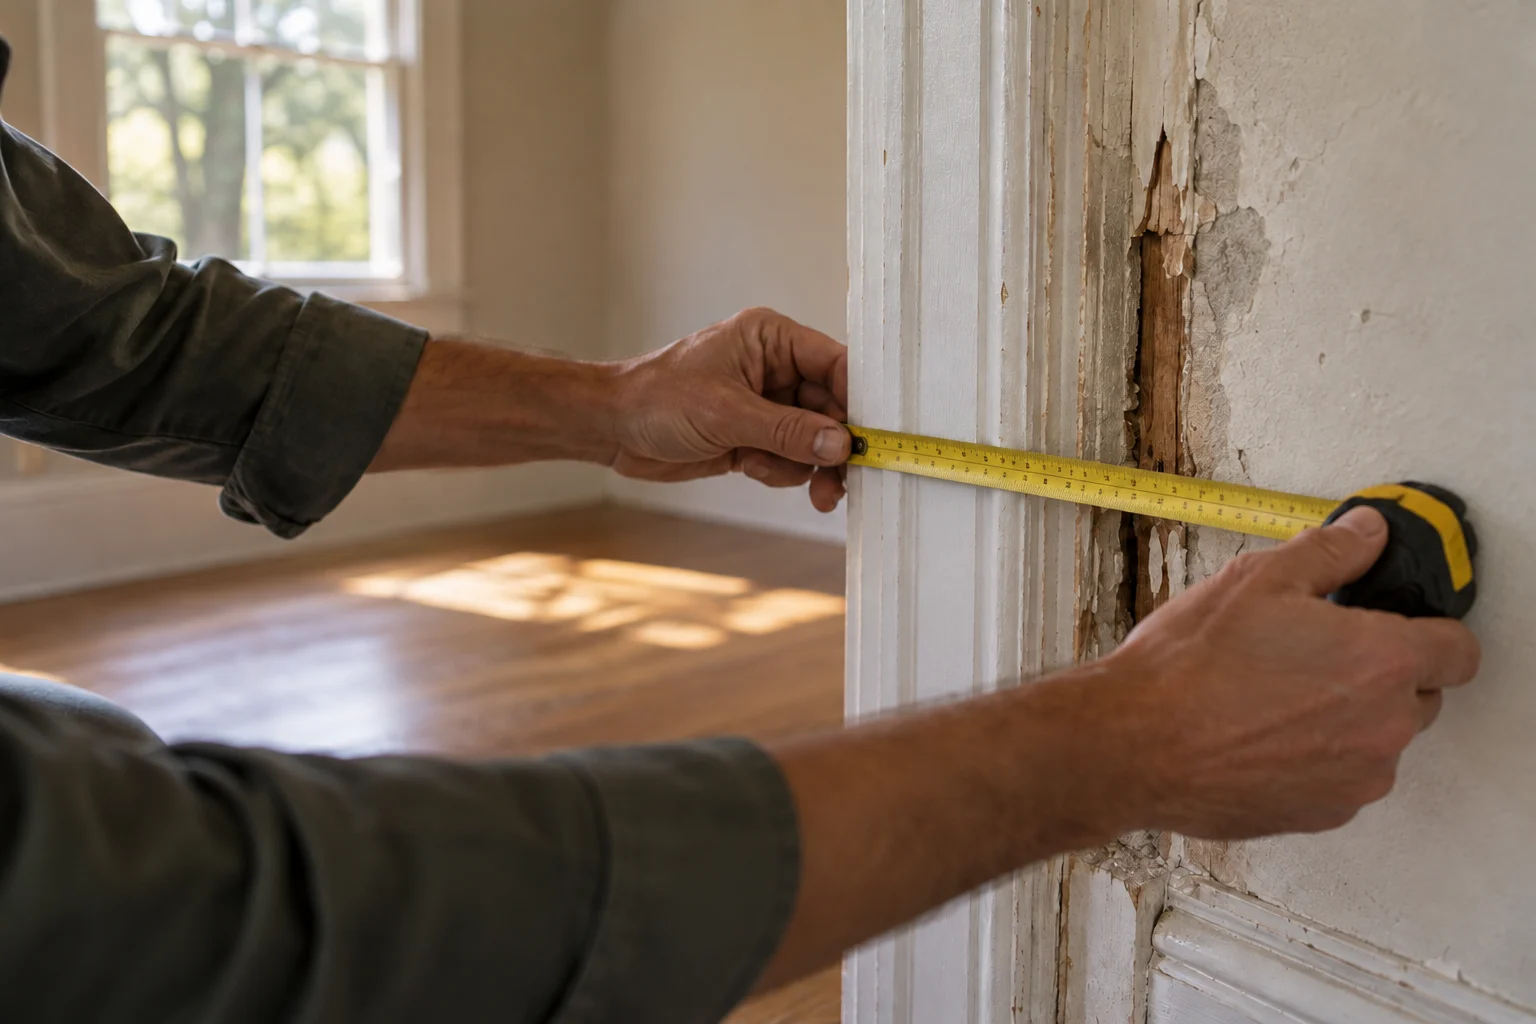
Prepare the file before an appointment
Do not climb onto a damaged roof to gather more evidence. Use the records from qualified professionals and preserve photos of any temporary repairs. If the roof has already been repaired, keep the original inspection material, invoices, and records of changes made during the work.
Our South Carolina experience includes Charleston, Columbia, Myrtle Beach, and Hilton Head. Bring the policy, both estimates, photos, and appraisal correspondence to the discussion. Review the scope, fees, and any prior claim involvement before an appointment. Our emphasis is on honest, explainable estimates and direct communication. The process should begin with those facts, not a promise of a roof replacement or a particular award.
A clearer next step
Let's talk about your property claim.
Tell us what happened, where things stand with your insurer, and what's still unresolved. We can discuss the work your situation needs and whether our services are a fit.