Public adjusting for property owners
Insurance claim assessment in South Carolina
Insurance claim assessment in South Carolina starts with a simple question: what is missing from the picture? You may have a repair quote, a short insurer estimate, and photos on your phone, yet still have no clear explanation for the difference. We bring those pieces together to review the damage and the progress of your claim.
This is a useful place to start when you are unsure whether the problem is a missing repair item, incomplete records, a payment calculation, or a question that needs a different professional.
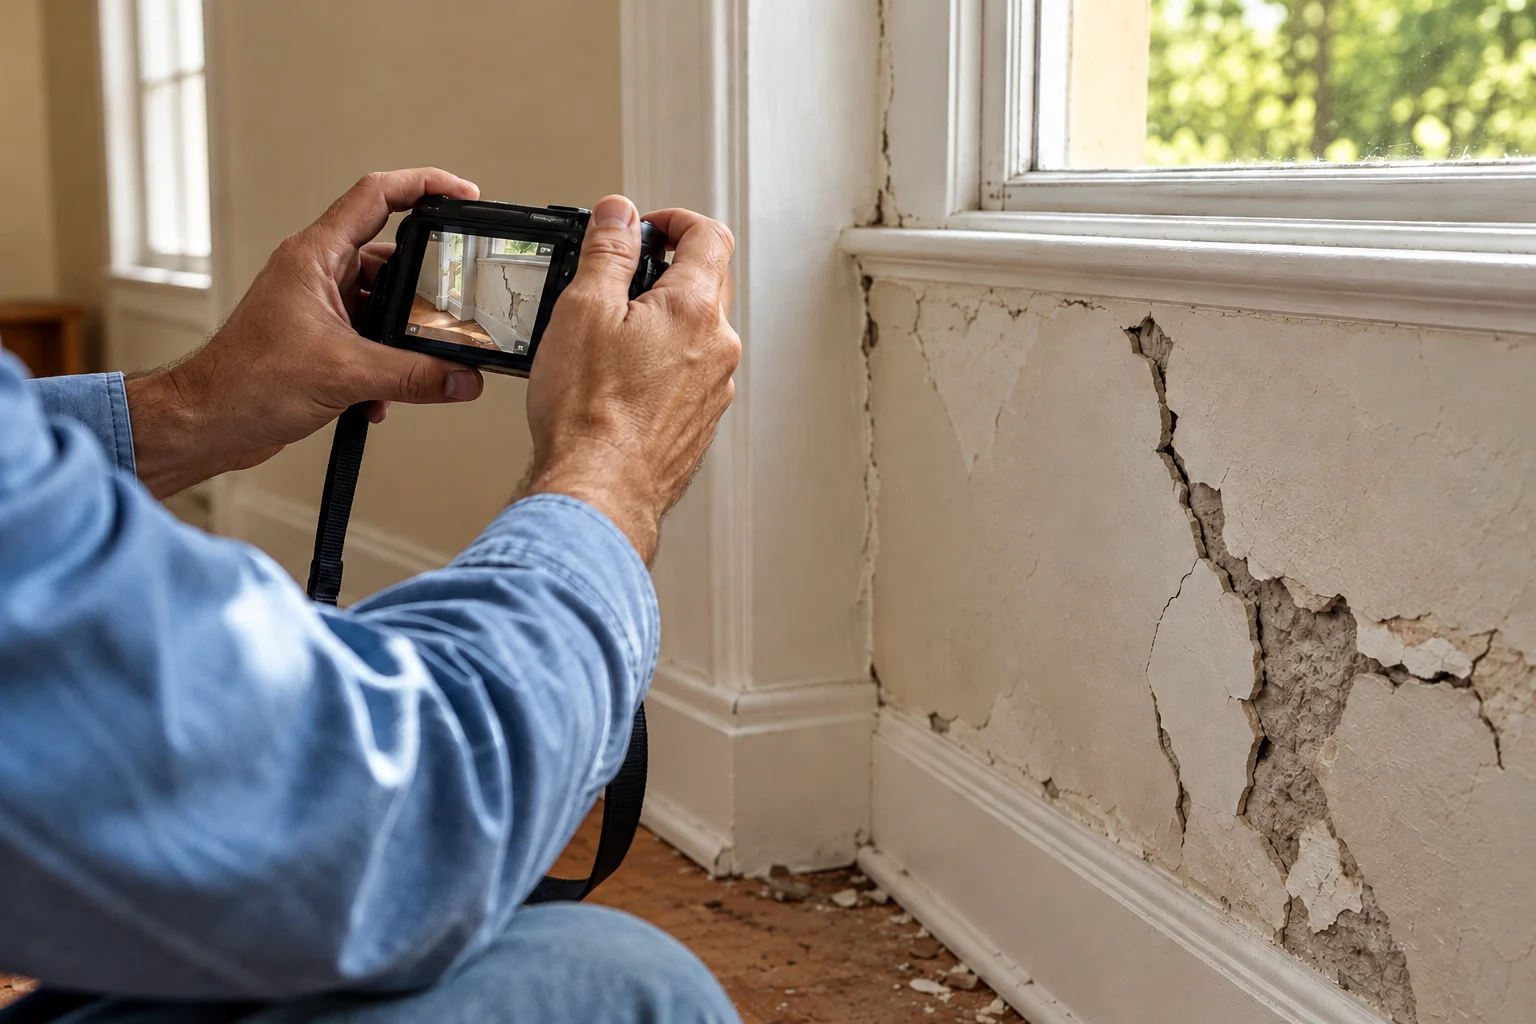
Insurance claim assessment
The review begins with the loss itself. What happened? When did you first notice it? Which rooms or parts of the property changed afterward? We then look at the records you already have and the insurer's response. A denial letter raises different questions from an estimate that recognizes the damage but lists very little repair work.
Try to separate what you know from what you suspect. A clear timeline helps keep the file accurate. If you do not know when a concealed problem began, say so rather than trying to fill the gap.
Comparing the damage with the paperwork
Two estimates can have different totals because they describe different work. One may include a damaged floor while the other also lists the work needed to reach and replace it. Measurements, quantities, and material descriptions need to be compared before a meaningful discussion about price.
We use photos and measurements to support that review. Our field and desk adjusting background helps us look at both the physical loss and the way it has been presented in the claim file. Our estimating work also draws on more than two decades of Xactimate experience.
An honest answer about the next step
An assessment does not mean every claim needs full public adjusting. Better records may resolve a question. An omitted repair item may need a supported supplement. If the dispute is about the amount of loss, a conversation about appraisal may be useful. Legal questions belong with an attorney.
Our approach is to be direct when we don't see a sound way to help. We don't want to add unsupported items or sell a property owner on a result the evidence cannot support.
What to gather before the review
Collect the complete policy, the insurer's estimate, payment letters, photos, repair quotes, and any invoices for work already done. Include the claim number and a short list of your concerns. You do not need to turn everything into a perfect report before talking with us.
Our experience includes losses around Charleston, Columbia, Myrtle Beach, and Hilton Head. Explain where the property is and whether an inspection or repair is already scheduled. Those details help us understand the stage of the claim and what needs attention first.
A clearer next step
Let's talk about your property claim.
Tell us what happened, where things stand with your insurer, and what's still unresolved. We can discuss the work your situation needs and whether our services are a fit.