Public adjusting for property owners
Denied property insurance claim assistance in South Carolina
Denied property insurance claim assistance in South Carolina starts with understanding why the insurer said no. A denial letter can leave you angry and unsure what to do, especially when the damage is easy to see. The useful first step is to identify the exact reason and the evidence behind it.
We can discuss the property claim records and the practical work that may be needed. We're direct about the limits of our role and don't promise that every denied claim can be turned around.
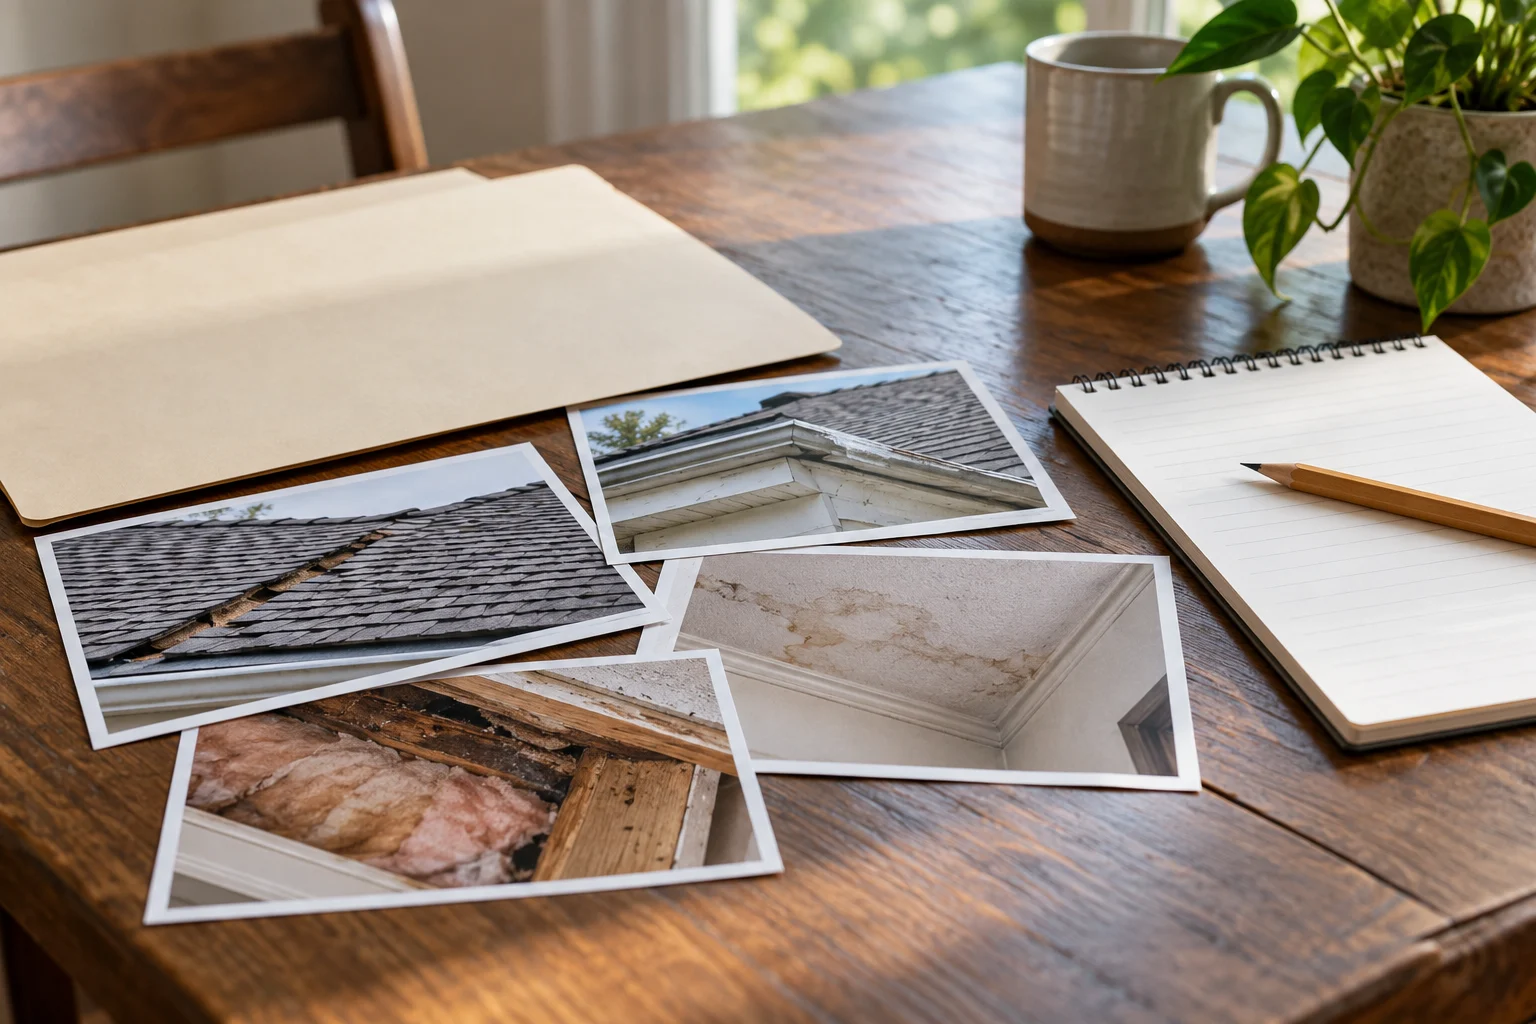
Denied property insurance claim assistance
Get the denial in writing and keep the complete letter. Look for the policy provision the insurer cites and its description of the loss. Compare that description with your records. Is the insurer working from the same dates, cause information, and inspection findings?
A factual error and a legal disagreement require different responses. A missing plumber's report might call for more documentation. A dispute about the legal meaning of a policy term may need an attorney. Knowing which issue you face helps you choose the right next step.
Gather evidence that addresses the reason
Sending more documents is not always the same as sending useful documents. Choose records that speak to the insurer's stated concern. Those may include dated photos, a professional cause report, repair history, or correspondence showing what was previously reported.
Be accurate about earlier damage and uncertainty. Our approach is to avoid unsupported estimates and claims that do not fit the facts. If the records show a longstanding condition, that should be part of the review rather than something to hide.
Do not confuse a denial with a price dispute
An insurer that accepts a loss but disagrees with an estimate presents a different problem from an insurer that denies the claim entirely. Appraisal may be relevant to an amount-of-loss dispute, but it should not be treated as an automatic answer to every denial.
We have experience with public adjusting and appraisal as separate roles. The right discussion depends on the policy, the insurer's position, and the work needed. Legal coverage advice or a lawsuit belongs with a qualified attorney.
Start with a realistic review
We bring years of field and desk adjusting experience, including work on the insurer's side that informs our public adjusting approach. That background helps us review how the claim was documented and where the record may be unclear.
For a property in eastern South Carolina, including Charleston, Columbia, Myrtle Beach, or Hilton Head, gather the policy, denial letter, photos, estimates, and reports. Note any dates or response requests in the correspondence. Tell us what you believe was missed and why. We can discuss whether there is useful claim work we can do, or whether another professional is better suited to the issue.
A clearer next step
Let's talk about your property claim.
Tell us what happened, where things stand with your insurer, and what's still unresolved. We can discuss the work your situation needs and whether our services are a fit.