Public adjusting for property owners
Policy coverage analysis in South Carolina
Policy coverage analysis in South Carolina can start with a sentence in a claim letter that does not make sense to you. The insurer may cite a limit, exclusion, or policy condition, while the repair estimate says something else. Before deciding what to do, you need the full policy and a clear record of the loss.
We help bring the claim facts and documents into focus. The goal is to understand the questions that need answers, without confusing a repair estimate with a promise that insurance will pay.
Policy coverage analysis
The declarations page is a starting point, but it is not the whole policy. Gather the policy forms, amendments, and endorsements that applied on the date of loss. Include the insurer's letters and any written explanation of how a payment was calculated.
Keep those records together with a short timeline. Note when the damage was discovered, when it was reported, and what inspections followed. This gives the review a concrete starting point instead of relying on a memory of a phone call.
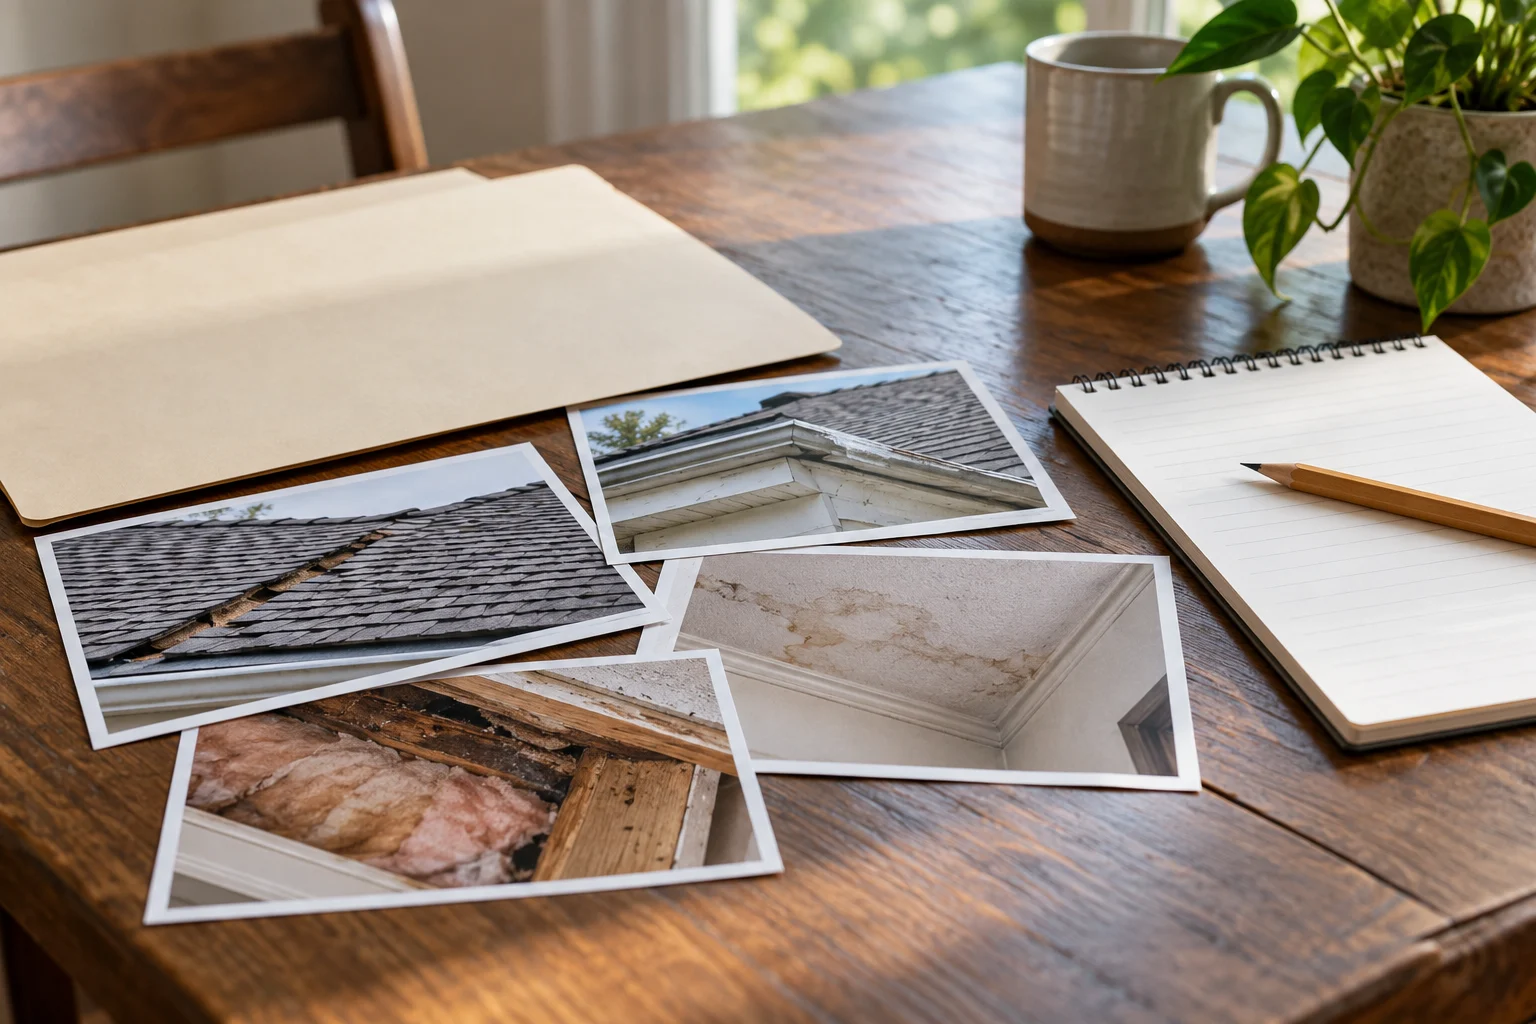
Separate the cause, damage, and repair cost
These are related questions, but they are not interchangeable. A photo may show a damaged wall without proving how the damage began. A contractor may price the repair without addressing a policy term cited by the insurer. Each part of the discussion needs the right evidence.
Our review focuses on the cause of loss, especially with water damage. Our years in field and desk adjusting help us recognize when the file needs a clearer description, a contractor's finding, or a better record of the affected areas.
Know what claim help can and cannot settle
A well-supported estimate explains the work and its cost. It does not replace the policy or settle every disagreement about its meaning. If your issue involves legal interpretation, litigation, or a contested coverage position, seek advice from a qualified attorney.
Our approach is to be straightforward about the limits of what we can do. We don't want to build an estimate around a loss the facts do not support. An early discussion about the real issue can help you avoid spending time on the wrong process.
Bring specific questions to the conversation
Useful questions include: Which document explains this deduction? Has the insurer addressed every damaged area? Is the disagreement about the repair amount or the reason for the loss? What further information has been requested? Ask for clear written answers when a decision is hard to follow.
For a property in Charleston, Columbia, Myrtle Beach, Hilton Head, or elsewhere in eastern South Carolina, start with the location and your current claim status. Send the full records rather than selected pages alone. We can discuss the practical claim work involved and when another professional should take the lead.
A clearer next step
Let's talk about your property claim.
Tell us what happened, where things stand with your insurer, and what's still unresolved. We can discuss the work your situation needs and whether our services are a fit.