Public adjusting for property owners
Hail damage insurance claims in South Carolina
Hail damage insurance claims in South Carolina need evidence from the property, not just a report that hail fell nearby. You may see dents on a gutter or hear that neighbors are replacing roofs, yet still be unsure what happened to your own home. A careful record helps separate the questions.
Our adjusting background includes years of wind and hail claim experience. We focus on the observed damage, the repair scope, and the documents needed to explain the loss to the insurer.
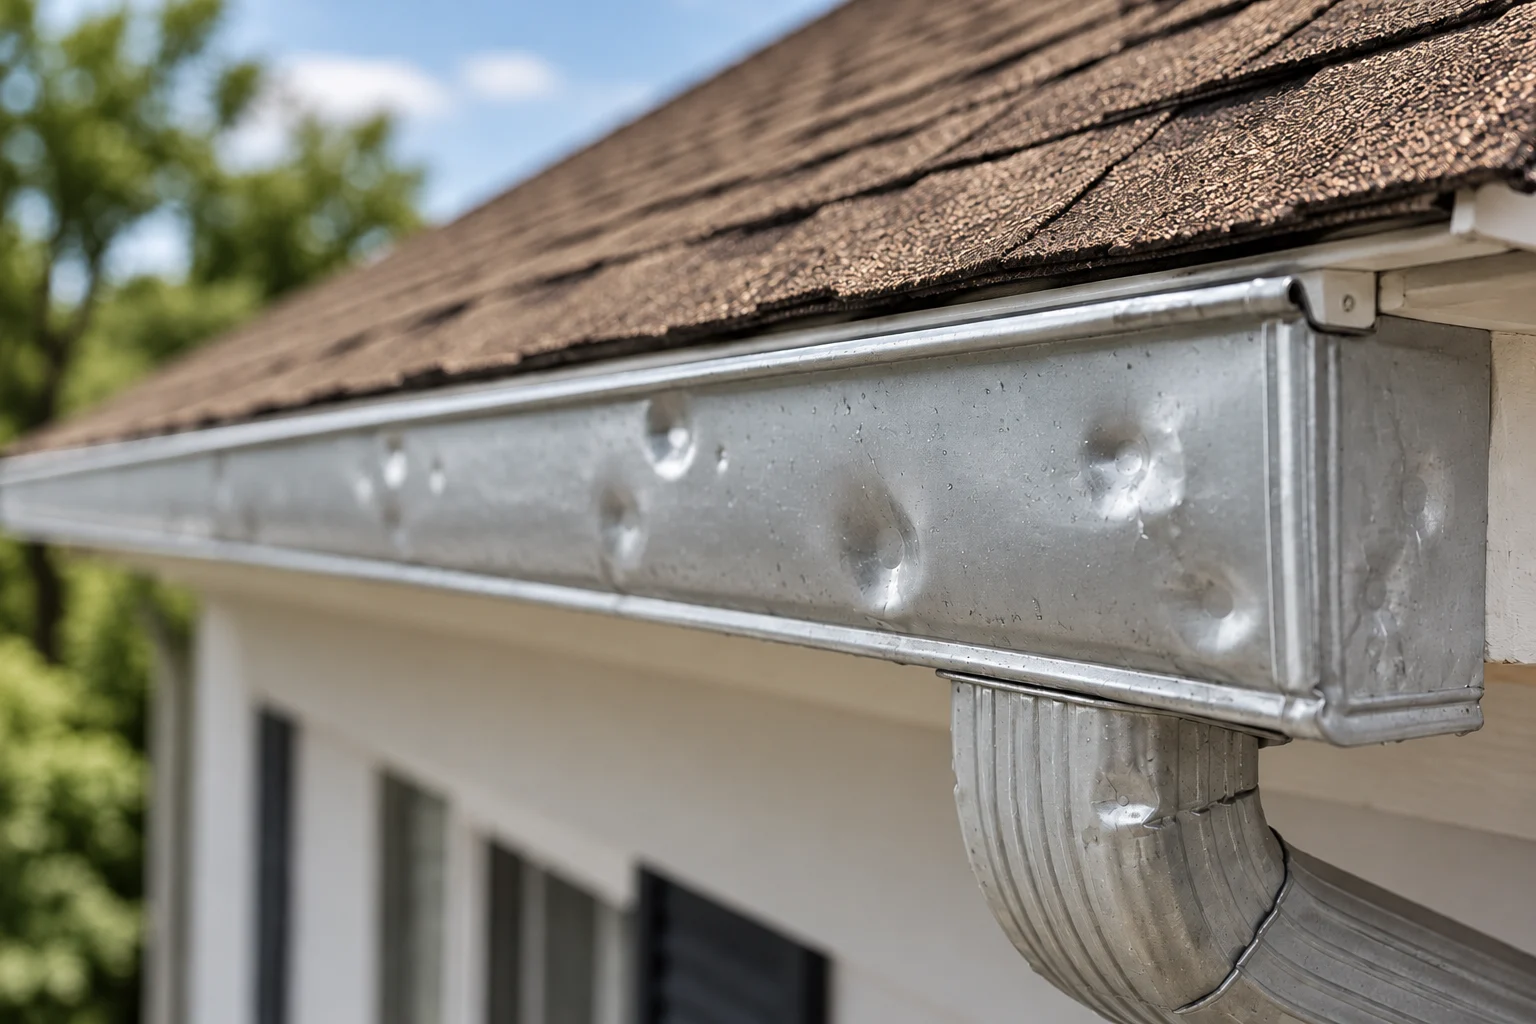
Hail damage insurance claims
Start with the date you noticed damage and any information you have about the storm. Keep photos taken before and after the event if they are available. A weather report can add context, but it does not show the condition of your specific roof, siding, or other property.
Ask the inspecting professional to identify the location and type of damage in the report. Wide photos show where an item sits. Closer photos show the detail. Both are more useful than a folder of images with no notes.
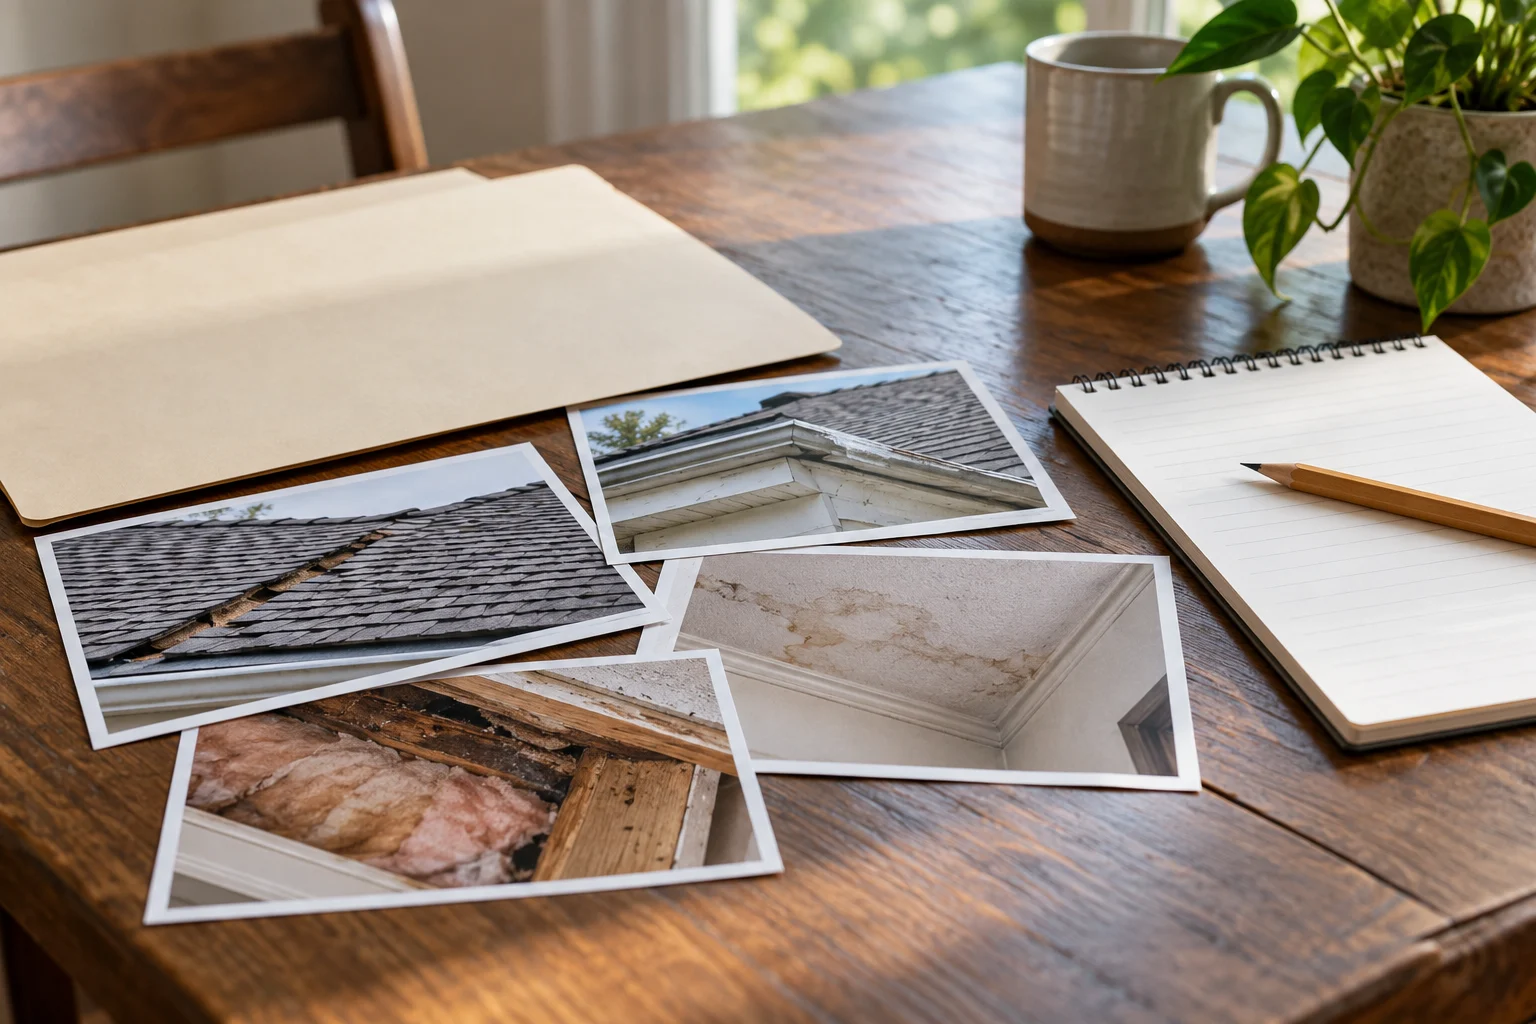
Look beyond a single roof photo
A hail claim may involve more than one surface. The inspection record should describe the areas actually affected and explain the work proposed for each. It should also identify existing wear or unrelated damage so those conditions are not mixed into the claim.
Our field experience helps us connect the inspection to an estimate. Our desk adjusting background also helps us review the file from the perspective of someone who must understand the loss through the documents, without standing at the property.
Make the repair estimate explainable
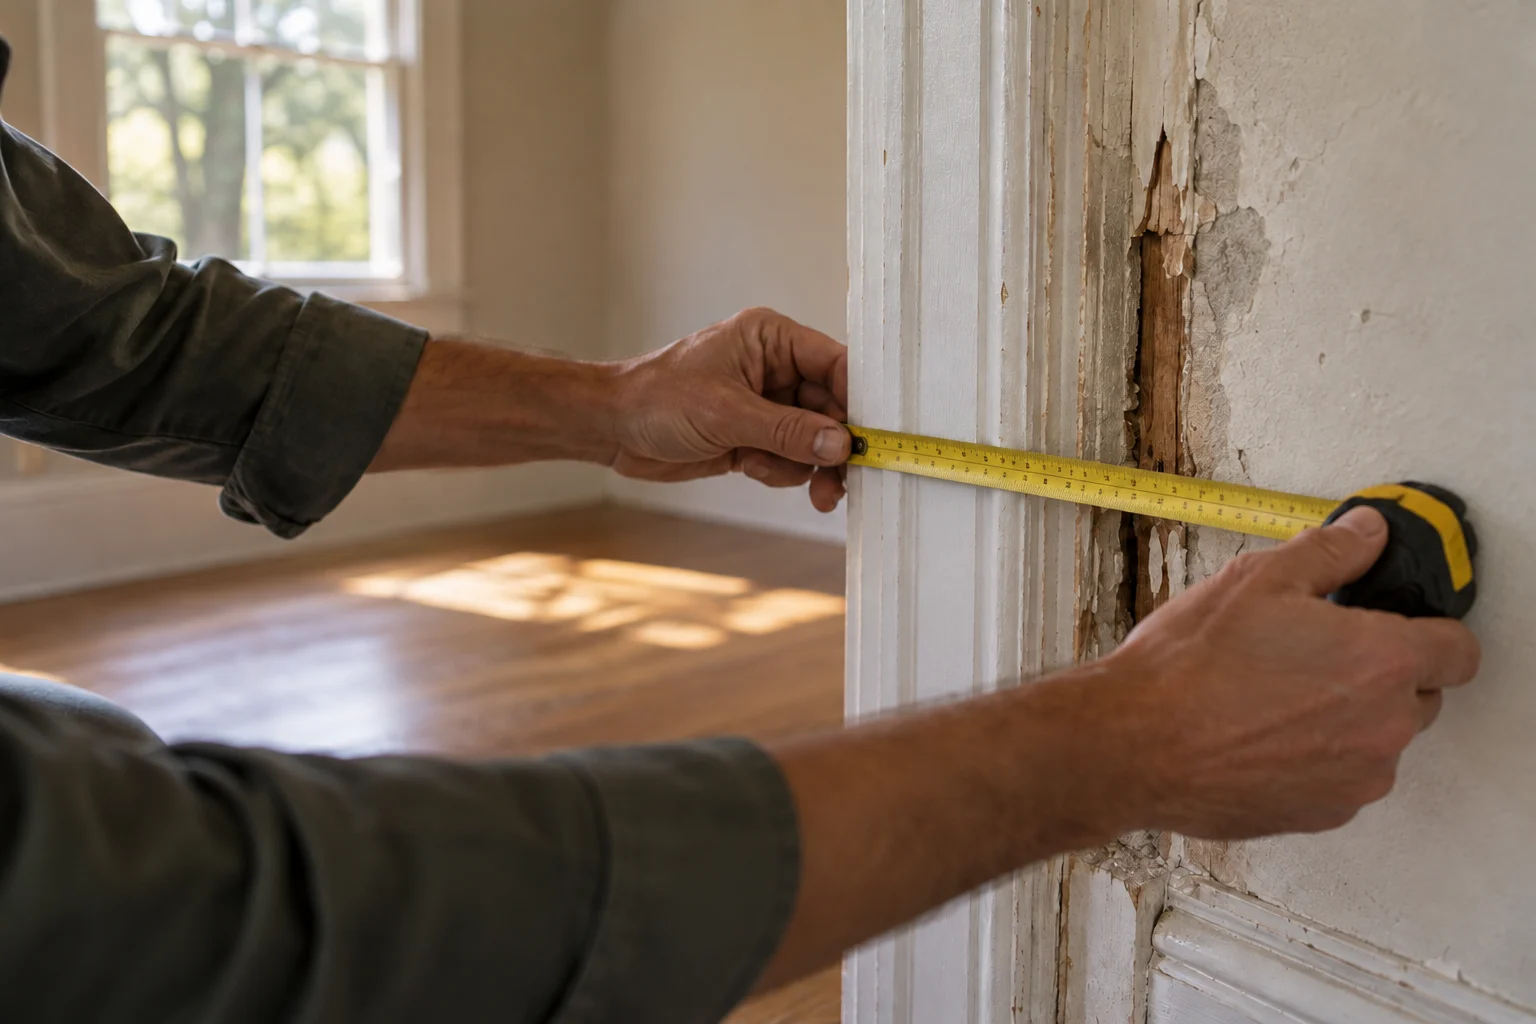
A contractor's quote and an insurer's estimate may use different measurements, materials, or repair assumptions. Before focusing on the final number, compare those details. If an item is missing, the response should show why the work is needed and what supports the quantity.
Our Xactimate estimating work draws on more than two decades of experience. Our aim is to document justified repairs. We don't treat the estimating software as proof on its own; the photos, measurements, and damage description must support the work.
What to do if the first response feels incomplete
Keep the insurer's inspection report, estimate, and letters together. Note which damaged items were addressed and which were not. If the carrier says there is no hail damage, request its explanation in writing and gather any professional findings that directly address that conclusion.
We work with property owners in eastern South Carolina, including the Charleston, Columbia, Myrtle Beach, and Hilton Head areas. Bring the claim records and roof history to the first discussion. We can review the evidence and explain possible next steps, without promising a new roof or a payment based only on the storm's presence.
A clearer next step
Let's talk about your property claim.
Tell us what happened, where things stand with your insurer, and what's still unresolved. We can discuss the work your situation needs and whether our services are a fit.